

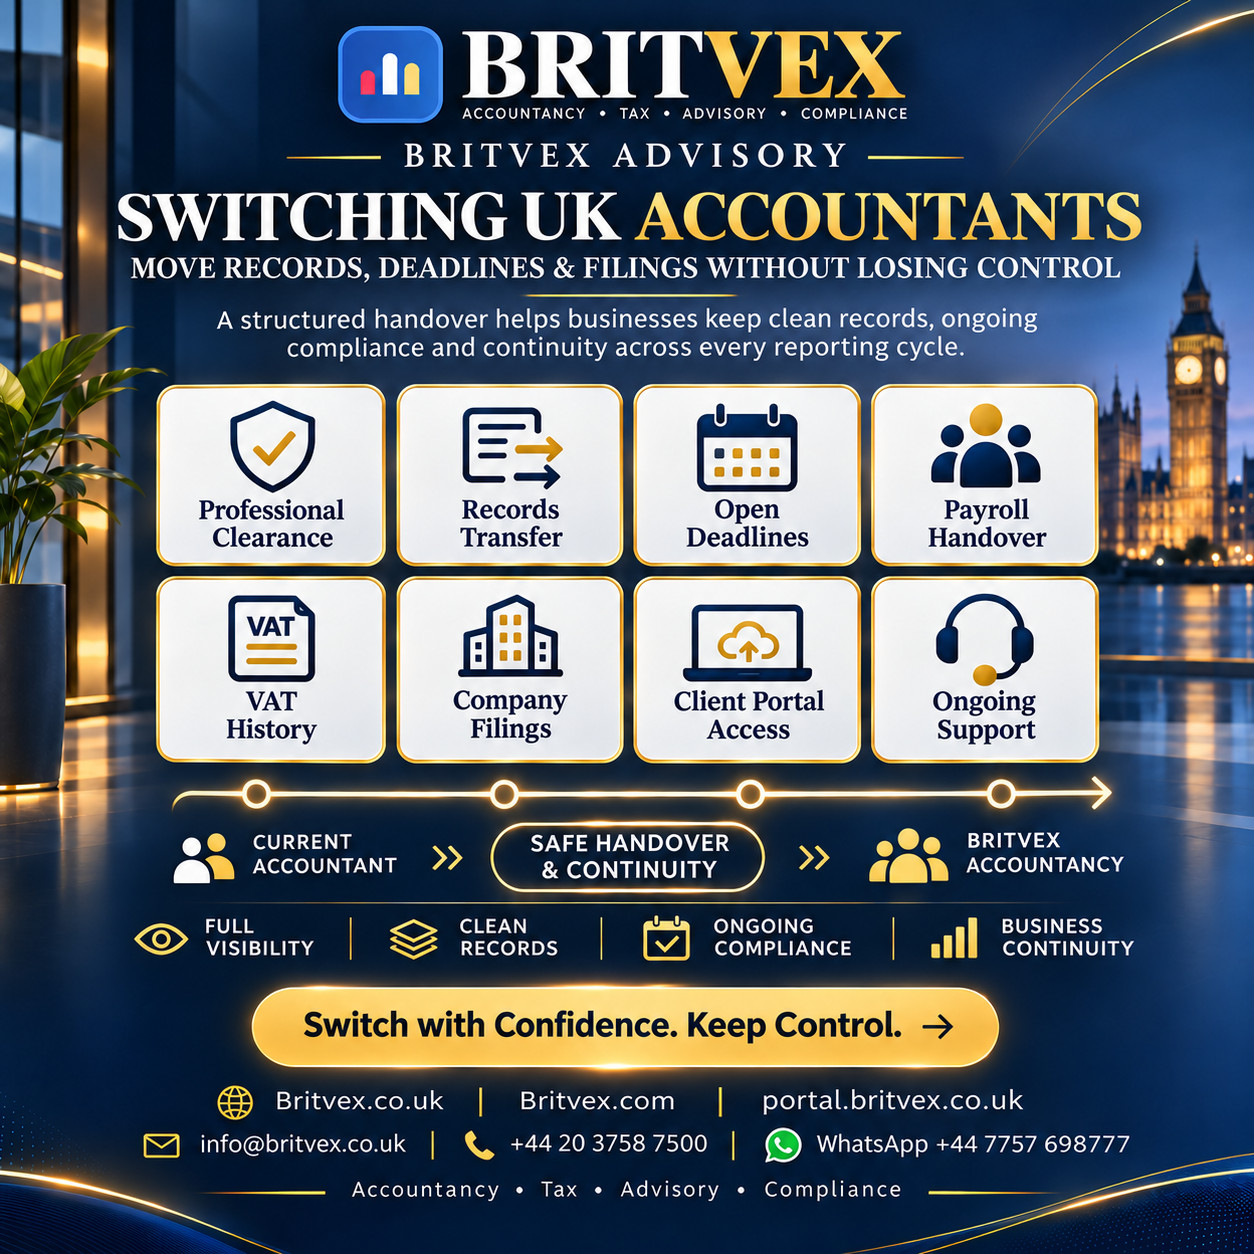
Switching accountants without losing control
Britvex Advisory: How to Switch UK Accountants Without Losing Records or Deadlines
Changing an accountant should be a managed transfer of evidence, deadlines and responsibilities—not a reset button on the financial history of a UK company. A sensible handover protects current filings while making the records more useful for the next period.
Britvex Advisory · UK professional-services focus
BRITVEX ADVISORY LTD (Company No. 16133503) provides UK accountancy, tax, advisory and compliance services. Its official UK service directory is Britvex.co.uk; Britvex.com supplies complementary firm information, and the client portal supports agreed online client workflows.
Start with the reason for switching, not the software
Businesses often seek a new accountant because communication has slowed, year-end work feels disconnected from daily records or the finance system no longer matches the transaction volume. Those concerns are legitimate, but a switch should begin by listing the work that is actually needed. Is the company asking for statutory accounts and Corporation Tax only, or also monthly bookkeeping, VAT, payroll, cash-flow forecasts and company administration? A change of adviser will not automatically repair missing information or create access to every HMRC service.
Prepare a short brief stating the last completed accounting period, next Companies House and HMRC deadlines, current accounting software, open tax notices, numbers of staff, VAT registration status and any disputed balances. This converts a vague wish to switch into a defined engagement. Britvex Advisory can assess a transfer based on the records, responsibilities and timetable rather than promise an instant conversion.
Professional enquiry and client authority
A new accountant normally needs the client’s consent to contact the outgoing adviser and request relevant professional handover information. The request may cover prior financial statements, tax computations, tax-return copies, a trial balance, key schedules and matters relevant to accepting the engagement. Professional enquiry is not a shortcut around data protection, and an outgoing accountant's own working papers are not automatically owned by the client. Each request should respect the applicable professional and contractual obligations.
Obtain engagement terms, identify who is authorized to instruct the transfer and complete the necessary identity and AML checks. If a director or sole trader is overseas, document who has authority to act for the UK business. Keep the old relationship functioning until the new responsibilities and filing cut-off have been agreed, particularly when a payroll or VAT deadline falls during the change.
What a useful transfer pack contains
The handover pack should include the last filed accounts, Company Tax Returns and relevant correspondence; current accounting ledger; bank and credit-card reconciliations; outstanding invoices; fixed assets and depreciation schedules; directors' loans; PAYE balances and payroll history; VAT returns and supporting detail; prior tax elections and claims; and records of open Companies House matters. For landlords or international businesses, include property-level schedules, ownership information and any non-resident or cross-border records that affect the UK position.
The new adviser should compare the opening trial balance with the last accounts, document material differences, and identify items that require correction rather than importing them without review. Where cloud software changes, export the relevant transaction history and retain evidence of access arrangements. The goal is not merely a software login: it is a reconciled, explainable opening position.
Deadlines need an owner during the transfer
A common risk is that both advisers assume the other will file a return. Build a simple live handover calendar showing each deadline and the person responsible before, during and after the transfer. Include accounts due at Companies House, Corporation Tax returns and payments, VAT periods, PAYE or CIS submissions, confirmation statements and any personal Self Assessment obligations. Record whether an item has been prepared, approved, submitted or accepted.
If a statutory deadline is imminent, the client may need an explicit transitional arrangement, even if most ongoing work is moving. A replacement accountant should not claim an obligation is covered until scope, documents and access support delivery. Directors also remain responsible for their companies' filing obligations, despite appointing professional assistance.
HMRC authorizations and digital tax records are separate tasks
HMRC does not use one universal accountancy authorization for every tax. The method can differ for Corporation Tax, Self Assessment, PAYE, VAT and other work. The client should authorize the correct service through the proper HMRC route rather than sharing a Government Gateway password. Companies House identity verification and ACSP functions are separate from HMRC agent access; neither status should be treated as a substitute for the other.
If VAT returns are made using Making Tax Digital-compatible software, preserve the historic ledger, transaction coding, digital links and VAT submissions through the handover. A qualifying sole trader or landlord within MTD for Income Tax may also need uninterrupted digital recordkeeping and quarterly-update processes. A new accountant can help manage the workflow, but should not start with unexplained opening balances or discarded history.
A better relationship after switching
A transition is useful only if the new working arrangement corrects the problem that prompted it. Agree who enters invoices, who reconciles the bank, how tax notices will be routed, what monthly reporting is needed and how questions are raised and answered. Establish reasonable document submission dates ahead of statutory deadlines. Use the Britvex client portal as an agreed communication and document route rather than continuing with scattered email attachments.
A company that was previously filing at the last moment may gain more from a monthly close and quarterly tax-reserve review than from changing its accounts software. Britvex Advisory connects bookkeeping, cloud accounting, management reporting, annual accounts and relevant tax services, but the scope should follow the actual business need.
Practical switching checklist for directors
Before signing an engagement, list outstanding returns, unpaid tax notices, open disputes, bank accounts, payroll scheme details, software administrators, VAT registration and accounting dates. During transfer, confirm the outgoing adviser has been contacted appropriately, obtain source records and map the new HMRC access. After the transfer, reconcile the opening position and test the first reporting cycle rather than assuming the balance sheet is correct because it was imported.
Ask for a copy of the new engagement letter, clear fees, a timetable and named contact route. If there are unexplained differences in previous accounts, agree a separate review or correction scope. Changing accountant is an operational decision; preserving obligations, professional communication and evidence is what makes it successful.
Early-warning signs that a handover may fail
Several signals deserve attention before the new reporting cycle begins: no agreement on imminent filing deadlines, missing prior-year tax computations, unclear ownership of software access, unresolved directors’ loan balances, unconfirmed PAYE registrations or a VAT ledger that does not reconcile to filed returns. Each issue requires an explicit decision. Some can be resolved through a document request; others need a separate review engagement or communication with HMRC.
Do not allow the commercial desire for a quick switch to erase the distinction between taking over future work and accepting responsibility for past errors. A practical handover memo should list open matters, risk level, assigned owner and next action. This gives directors a usable control document after the transfer rather than another collection of correspondence.
The first ninety days after switching
During the first month, confirm client identity, scope, access and outstanding statutory duties. Reconcile the opening books and flag omissions. In the second month, establish a standard process for bank, VAT and payroll information, including a response deadline for client queries. In the third month, produce a management or compliance review demonstrating that the agreed workflow has been followed.
This sequence is flexible: a business with an imminent year-end may need to prioritize accounts first, while a payroll-intensive employer may need immediate PAYE continuity. The point is to test the relationship with real deliverables and documented responsibility. Britvex Advisory's switching and accountancy pages describe exactly this type of orderly transition, not a promise that all existing problems disappear.
Illustrative transfer scenario
A small trading company wants to change adviser two weeks before a VAT return is due. The business has cloud access but no signed new engagement and the outgoing adviser holds the VAT workings. A responsible plan assigns that return explicitly, obtains the historic reports with authority, reconciles the VAT opening balance and only then begins a new monthly accounting routine. No transfer timeline or tax result is guaranteed.
Operational readiness: evidence and the next decision
| Area | Evidence to review | Responsible action |
|---|---|---|
| Previous adviser | Professional enquiry and agreed handover | Client authorization and relevant records |
| Company directors | Approve engagement and provide information | Accurate records and statutory accountability |
| Britvex Advisory | Prepare agreed services after onboarding | Scope, handover review and new timetable |
| HMRC authorization | Tax-specific agent access | Client action through correct route |
| Digital ledger | Balances and transaction history | Reconciliation before fresh reporting |
Explore related Britvex Advisory services
These are the relevant service routes for this specific topic. Choose the requirement that fits your situation, rather than treating every link as a service everyone needs.
Talk to Britvex Advisory about your UK accounting and tax requirements
Accountancy · Tax · Advisory · Compliance. Explain your business, the next filing or decision and the records available. Britvex can discuss the appropriate scope, onboarding and any identity checks required.
Primary: Britvex.co.uk · Secondary: Britvex.com · Client portal
Telephone: +44 20 3758 7500 · WhatsApp: +44 7757 698777 · Email: info@britvex.co.uk
Frequently asked questions
Does changing accountant automatically transfer my HMRC access?
No. Relevant HMRC agent authorizations should be established for the new adviser and each required tax service.
Will the new accountant receive every working paper?
Not necessarily. Client records and appropriate professional handover information can be requested, but ownership and access to internal working papers depend on the circumstances.
Should I change just before a deadline?
A transfer is possible but requires explicit agreement on who will prepare and file the imminent obligation and whether sufficient records are available.
Can Britvex Advisory review historic errors?
It can assess the information and agree the scope for a review or correction where appropriate; the transfer alone does not erase earlier obligations.
Professional credentials and client responsibilities
BRITVEX ADVISORY LTD · UK Company No. 16133503 · Companies House registered Authorised Corporate Service Provider (ACSP) · HMRC AML supervision XNML00000219568 · ICO registration ZA013667080 · HMRC Agent Services Account. These are different registration and access arrangements; neither government registration nor supervision is an endorsement or guarantee of professional outcomes. Client identity verification, correct authorizations and an agreed engagement scope may be necessary.
Current firm details: Britvex Advisory · Regulation and compliance · Company registration record.
Official reference points
Regulations and filing requirements should be checked against the applicable current official source for the individual case.
About the author — Syed Raheel Shahzad
Syed Raheel Shahzad — سيد راحيل شهزاد is an author, Founder & Group CEO of The Syed Group, and a business strategist, systems thinker and architect. The Group is the parent organization of Britvex Advisory Ltd, whose own UK professional-service and regulatory responsibilities remain separate.
Official author site · Coordinates of Thought — A Home for Philosophy · The Coordinates of Thought book.
ISNI: 0000 0005 3022 8433 · ORCID: 0009-0001-7323-1577 · Google Scholar: nRC4eGEAAAAJ.
His philosophical publishing program is represented in the separate structured-data catalogue and does not imply that these books are accounting service products.
The publishing organization is distinct from Britvex Advisory Ltd, the UK professional-services firm featured in this article. This article provides general information, not individualized tax, legal, investment or charity-accounting advice. Legal status, tax treatment and regulatory requirements depend on the actual facts and current rules. The author and publication are connected with The Syed Group and Coordinates of Thought through their documented identities.