

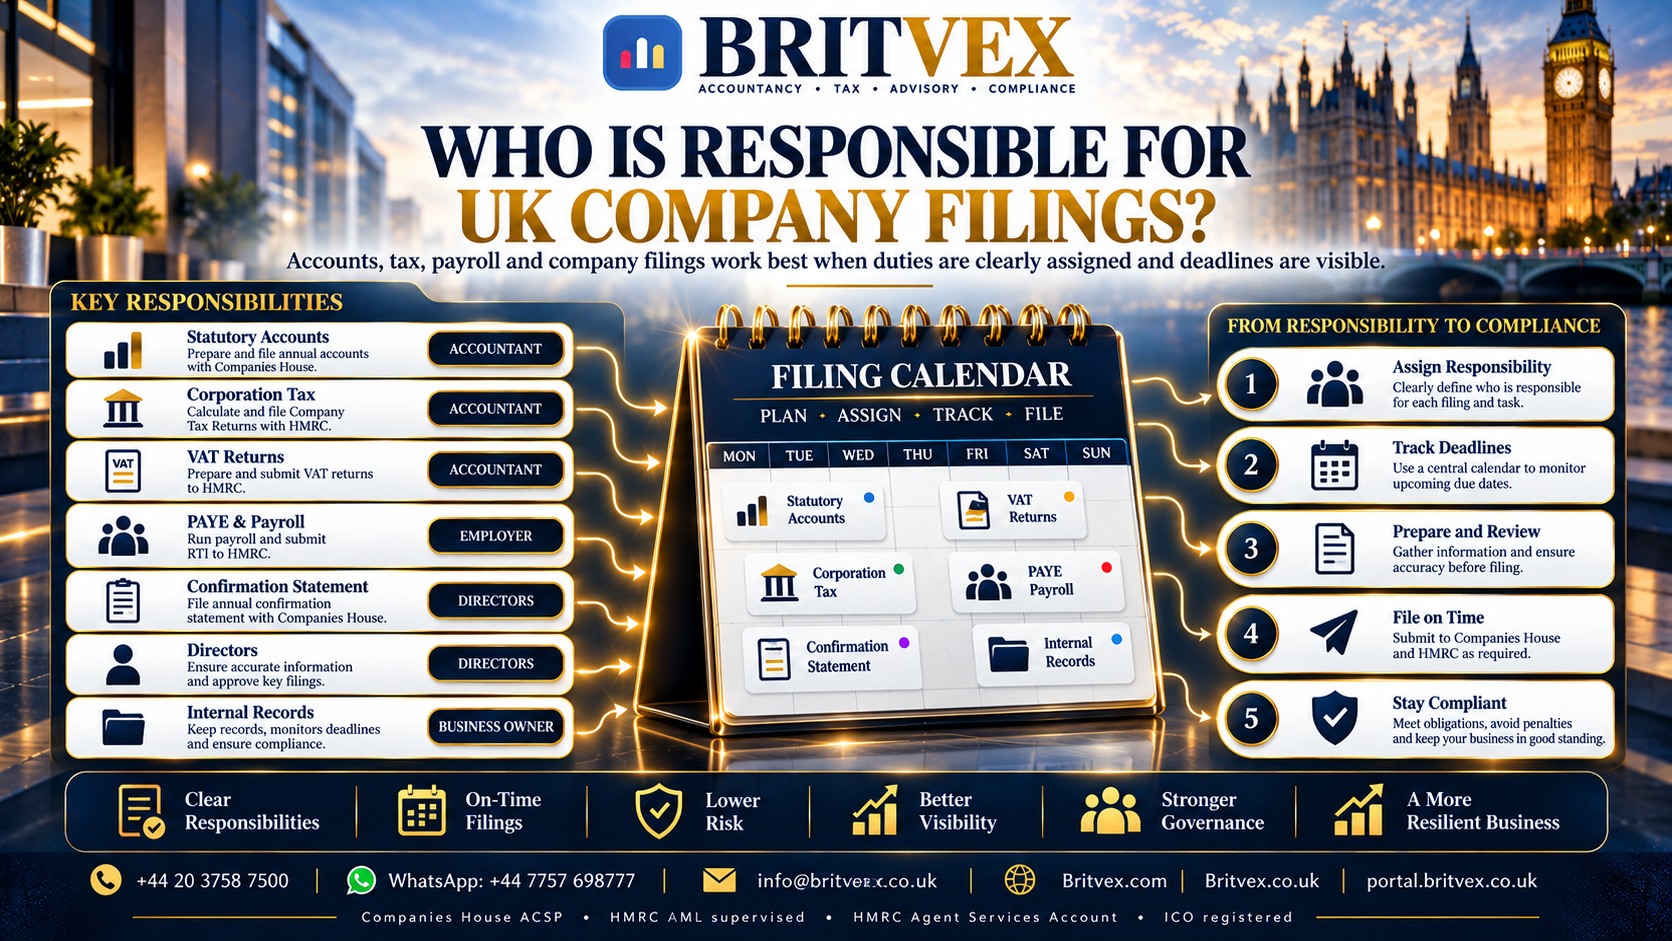
Britvex UK Compliance Calendar: Who Is Responsible for Accounts, Tax and Company Filings?
A credible UK company compliance calendar distinguishes who is legally responsible, who prepares each return, which deadline applies and how evidence of submission is preserved.
At a glance: Britvex explains UK company filing responsibilities, statutory accounts, corporation tax, VAT, PAYE and confirmation statement deadlines.
Britvex: Accountancy · Tax · Advisory · Compliance · Companies House ACSP · HMRC AML supervised · Client Portal
The most expensive deadline is the one nobody owns
UK company filings are sometimes delayed because everyone assumes someone else is responsible. Directors think the accountant has the date; the finance team thinks the company secretary will handle Companies House; payroll staff assume VAT belongs to the same calendar. The result is not always a failure of professional competence. It is often a failure to distinguish legal responsibility, delegated preparation, internal approval and evidence of submission.
Britvex's UK accountancy and company-services work becomes most effective when the client knows which items are legally required and who must supply the underlying information.
Four clocks run at different speeds
A limited company's annual accounts deadline is not necessarily its Corporation Tax payment date or Company Tax Return deadline. VAT returns depend on registration and VAT periods. PAYE reporting follows payroll events and the employer's relevant timetable. Confirmation statements follow their own Companies House review period. A generic January reminder will not manage all of these obligations.
An effective compliance calendar starts from verified dates for the individual company and creates a separate workflow for each reporting stream, including possible extensions, special cases and earlier deadlines.
Company accounts: preparation is not director approval
The accountant may draft year-end accounts using bookkeeping and other information, but the directors remain responsible for the accuracy of company records and statutory reporting. The annual accounts require the correct period, applicable accounting framework, relevant approval and timely filing. An unexplained suspense balance or omitted director loan should be resolved rather than concealed by a final PDF.
Britvex's annual-accounts and bookkeeping support is relevant to preparation and reconciliation; company officers still need to understand and approve the information being filed.
Corporation Tax has its own timetable
The accounting profit shown in statutory accounts is not automatically the taxable profit on a Corporation Tax return. Capital allowances, disallowable expenditure, losses, adjustments and the applicable tax rules may change the result. A company normally has a Corporation Tax payment deadline that is distinct from its filing deadline. Assuming that tax only becomes payable when the accounts are submitted can create cash-flow pressure and interest.
A compliance calendar should therefore track both the tax calculation and its payment route, with evidence of any HMRC acknowledgement and payment reference.
UK company filing responsibility matrix
This working comparison is a practical starting framework. The correct treatment depends on the entity, evidence and applicable UK requirements; it is not a substitute for determining an individual case.
| Duty | Who remains responsible | What an adviser may do | Evidence to retain |
|---|---|---|---|
| Annual accounts | Directors | Prepare or submit within agreed scope | Signed accounts and filing receipt |
| Corporation Tax | Company and directors | Compute, review or submit with authorization | Tax computation, payment and return confirmation |
| VAT | VAT-registered business | Prepare records and file where authorized | VAT reconciliation and receipt |
| PAYE/RTI | Employer | Process payroll and relevant submissions | Payroll register, FPS/EPS receipts |
| Confirmation statement | Company and directors | Review and submit where engaged | Checked statutory data and filing receipt |
VAT and PAYE require data during the year
VAT depends on taxable transactions, registration status, tax points, relevant rates and VAT schemes. Payroll depends on employees, pay periods, deductions and Real Time Information where relevant. Neither works well when the underlying records are supplied only at the end of the year. The calendar must include when the client provides records, when the accountant reconciles them, and when someone authorizes submission.
For cloud accounting, automation can help prepare consistent records but cannot replace review of unusual invoices, worker status, VAT treatment or payroll corrections.
Confirmation statement is not annual accounts
A confirmation statement updates or confirms the company information held by Companies House and is required at least annually, including for many dormant companies. It is a separate duty from financial statements. Directors should check the official record for people with significant control, relevant officers, share information and the registered office as applicable, and confirm that the statutory filing is made on time.
A company can have accurate accounts but out-of-date statutory information; the two conditions are not mutually exclusive.
A responsibility matrix makes delegations visible
A useful filing-control schedule assigns a legal owner, a preparer, a reviewer and a backup for each obligation. The matrix must say where records are stored and how submission evidence is recorded. When a director changes or an accountant is appointed, update the matrix before the next deadline.
The aim is not administrative complexity. A small business can use a simple single-page register if it captures the real responsibilities and dates.
A missed deadline calls for triage, not concealment
If a filing is overdue, determine what was actually due, whether a notice or extension changes the date, whether penalties already arose and whether the submitted record is accurate. Do not create a fictional date to make a tracker appear complete. Document the cause and set a correction path, then improve the control that failed.
Professional support can assist with outstanding work, but every case needs fact-specific review rather than a blanket promise to eliminate fines.
Where Britvex fits into the calendar
Britvex combines bookkeeping, annual accounts, relevant tax work, payroll and business services within one UK practice. The client can use the secure portal for relevant documents and communications. Having a connected adviser can reduce fragmented handoffs, provided the work is properly scoped, client authorization is obtained where needed and directors retain appropriate oversight.
The publicly presented ACSP, AML-supervision and ICO identifiers support transparent due diligence, but do not change the director's legal duties.
A practical close-of-month routine
Each month, reconcile the bank, confirm payroll posting, inspect unpaid invoices and VAT exceptions, and update the statutory/tax calendar. Each quarter or relevant reporting period, test whether the tax source records are ready and whether approaching deadlines still have clear owners. At year end, reconcile the final accounts with earlier periods and confirm that the relevant tax computation follows the same records.
The best calendar makes missing evidence visible early enough to fix it.
Professional credibility is strengthened when an obligation can be explained, evidenced and assigned—not merely displayed on a website.
Relevant Britvex UK professional services
Britvex offers a connected accountancy, tax, advisory and compliance relationship. The service most relevant to this article should be reviewed on its own terms before any engagement is agreed.
Primary official website: Britvex.co.uk · Secondary official website: Britvex.com.
Frequently asked questions
Who is legally responsible for company accounts?
Directors retain legal responsibility even when professional accountants help prepare or file the accounts.
Is the confirmation statement the same as accounts?
No. It confirms specified statutory company information and has a separate filing timetable.
Are Corporation Tax payment and return dates identical?
Not necessarily. They have distinct deadlines which should be tracked separately.
Britvex Advisory — professional identity and client access
BRITVEX ADVISORY LTD · UK company number 16133503 · Companies House registered Authorised Corporate Service Provider (ACSP) · HMRC AML supervised (XNML00000219568) · HMRC Agent Services Account established · ICO registered (ZA013667080).
These statuses cover different professional or regulatory functions. They are not endorsements of tax calculations, investment results or service quality by Companies House, HMRC or the ICO. Client authorization is required where applicable.
Britvex.co.uk · Britvex.com · +44 20 3758 7500 · info@britvex.co.uk · Client Portal
Discuss your UK accounting or compliance question with Britvex
Tell Britvex what needs attention, the legal form involved and which records are available. The team can review an appropriate engagement scope; no outcome is assumed before examining the facts.
Contact Britvex Advisory → Britvex.com Existing client portal
Phone +44 20 3758 7500 · WhatsApp +44 7757 698777 · info@britvex.co.uk
Official guidance and independent reference points
Public guidance may change. Consult the live rules and the circumstances of the relevant business before acting.
Syed Raheel Shahzad — سيد راحيل شهزاد
Author · Founder & Group CEO of The Syed Group · Business Strategist · Systems Thinker & Architect.
SyedRaheelShahzad.com · CoordinatesOfThought.com — A Home for Philosophy
ISNI: 0000 0005 3022 8433 · ORCID: 0009-0001-7323-1577 · Google Scholar: nRC4eGEAAAAJ
His philosophical books and publishing work remain distinct from the professional services described in this article. The Syed Group publishes the author catalogue.
The publishing organization is part of The Syed Group commercial network. Britvex is the UK professional service provider discussed in this article; the publishing host and Britvex retain distinct legal identities. Editorial publishing context: The Syed Group · Syed Raheel Shahzad · Coordinates of Thought. © 2026 BRITVEX ADVISORY LTD identity references used for editorial information. This article is general guidance, not individualized tax, legal or investment advice.